Author name: WealthEx Capital

Investor Guides

Why UK Investors Are Buying Dubai Property in 2026: A Guide for British Buyers

If as a landlord in the UK you’ve ever experienced it, then the rules regarding mortgage interest which reduce your tax relief, the extra stamp duty applicable to each additional property, and the constant stream of new regulations affecting private landlords are all factors that do not make buy-to-let entirely impossible but do alter the calculations, with an increasing number of British investors now questioning whether their next property should be located in the UK. More and more, the response is Dubai. At present, British buyers are either at or near the top of the foreign buyer rankings. In early 2026, UK nationals came in second place, after Indian buyers, accounting for about 13% of foreign purchasing activity, as shown by figures from the Dubai Land Department, while one agency’s figures for March to April 2026 actually ranked British buyers as first. Although the exact shares vary depending on the period and the dataset in question, the general trend is clear: the British are one of the largest groups to be buying property in Dubai. Why British Investors Are Looking at Dubai The Tax Picture Looks Very Different The first point that most UK clients bring up is that Dubai does not have an annual property tax, no personal income tax on rent, and no capital gains tax applicable to individually owned residential property. The major initial expense is the registration fee charged by the Dubai Land Department, which is generally 4 per cent of the purchase price. When you compare this with the UK’s stamp duty surcharges on additional properties, the limitations on mortgage interest relief, and the capital gains tax on disposal, the amount you end up keeping can be considerable. It should be clear that, if you are a tax resident of the UK, you are usually liable in the UK for all your income worldwide, this covering rent received abroad. The fact that Dubai does not tax this income does not mean that you will have nothing to pay in the UK. Although there is a double taxation agreement between the UK and the UAE, as to how it applies in your case you should consult a UK tax adviser before you purchase, not after. Yields That Beat Most UK Markets The rental yields available in Dubai’s existing communities are typically in the 5-9% range, whereas UK investors generally obtain lower yields in the south of England when costs are taken into account. Since these figures are gross, the service charges, vacancy losses and management fees must be deducted if you are to make a fair comparison. The Pound Has Stretched Further Although exchange rates change, in recent periods the pound has purchased a substantial number of dirhams, thus improving the amount that a buyer in the UK can obtain. Since the dirham is pegged to the US dollar, the level of purchasing power you have depends on the pound-dollar rate at the moment that you make the exchange. Currencies can work in your favour or against you, so it is advisable to consider the timing and the transfer costs rather than assuming that the rate will remain favourable. Residency and Lifestyle An investment valued at AED 2 million or above will qualify an investor for the ten-year UAE Golden Visa, covering their immediate family as well. A number of our British clients begin by considering an investment and end up treating Dubai as a second home, or in some cases as their main home. We set out the eligibility criteria and the application process in our guide on the [UAE Golden Visa obtained via real estate investment](/blog/uae-golden-visa-real-estate-investment). Off-Plan Opportunities Dubai has a great deal more off-plan property than London, frequently offering payment plans that are structured so that the cost is paid over the course of construction. This is advantageous for investors who wish to deploy their capital gradually, though it involves greater risk than purchasing a completed unit, which is why the developer’s record is important. What UK Buyers Should Get Right Funding the Purchase A number of UK buyers use money from their savings or from the proceeds of selling their property. In other cases they consider releasing equity from their UK property or obtaining a mortgage in the UAE. Lending conditions in the UAE have become more strict for certain buyers, and investors as well as people taking out mortgages on a second home are generally given a lower loan-to-value ratio than first-time buyers, so it’s important to find out in advance how much you can actually borrow. Before transferring any money, it’s advisable to consult a UK mortgage broker or financial adviser, particularly if you plan on using equity from a UK property. Budget for the Full Cost In addition to the price and the registration fee, you should also provide for agent’s fees, service charges, and management fees if you plan on letting out the unit. Buyers who compare the gross yield shown in a brochure with their own net yield are usually disappointed, and this is the mistake we see most often. Be Selective About Location and Developer The market in 2026 is now more selective, with slower price growth, increasing new supply, and well-positioned communities that have genuine demand from end users performing better than those that are oversupplied. If you’re considering the timing, our analysis of [whether Dubai real estate prices will crash in 2026](/blog/will-dubai-real-estate-prices-crash-2026) looks at what the data indicates. Small units in existing communities are in demand among buyers who are looking for rental income and find it easier to resell. Be Honest About Risk Dubai should not be considered a sure thing. For a while regional tensions may impact feelings about it, the forthcoming supply might ease some of the pressure, and any investment in it should be based on how much you are able to afford to hold during a quieter period. It should be seen as a way of diversifying your portfolio rather than as a substitute for the entire portfolio.
Uncategorized

Will Dubai’s real estate prices experience a crash in 2026? What the data really shows

It’s one of the very first questions that most clients ask us before making a decision, and actually it’s a reasonable question. Since Dubai’s property market has experienced such a dramatic rise over the last few years, the issue isn’t really one of growth coming to an end, but rather whether it will finish like many previous Dubai property cycles have done, with a sharp correction that ends up affecting late buyers badly. Let’s instead consider what is actually taking place, rather than depending on either the “Dubai never goes down” marketing statement or the “it’s definitely a bubble” kind of skepticism which appears just as frequently in the comment sections. What the 2026 Numbers Actually Say Begin with the headline figures since they tell a more detailed story than either of the extremes indicates. In 2025 Dubai achieved a transaction value of about AED 682.5 billion from more than 214,000 sales, a significant increase compared to the previous year. This trend continued into 2026, with the first quarter alone seeing approximately AED 252 billion in transactions, representing a 31% year-on-year rise in value. At the same time, the number of active investors increased, new investors being up by double digits on the previous year. That doesn’t sound like what a market would be like in the early phases of a collapse. Yet the nature of the growth rate has obviously altered. Price appreciation, which had reached as high as 12 to 22% per year in 2024 and 2025, is now expected to ease down to between 5 and 10% in 2026 according to the source and the particular segment. Rental growth has also cooled more noticeably, having slowed to about 4 to 6% across cities after surging above 15% just a few years ago. In simple terms, the market is still growing, but the rate of growth has halted; that is a quite different situation from a crash. Why This Looks Like a Cooldown, Not a Correction It is due to a number of structural features that the year 2026 appears to be different from the earlier Dubai cycles which had a bad ending. Supply Is Rising, But So Is Absorption In 2026 about 120,000 to 131,000 new residential units are expected to be delivered, which is a marked rise compared with previous years. A figure like that would concern anyone who remembers the oversupply crash in Dubai between 2008 and 2009. The difference this time around is that demand has kept up. The population in Dubai is still increasing, foreign investment is rising, and the investor base has grown by about 8% year on year, indicating that the new supply is being taken up rather than remaining unsold. The Market Has Become More Selective, Not Weaker This is probably the most important point to grasp. Prime, low-density, and master-planned areas—such as Palm Jumeirah, Dubai Hills Estate, and Emirates Hills—still have strong resale activity and involve only limited discounting, while over-supplied or poorly situated developments are now experiencing actual pressure on their prices. The fact that there is this kind of divergence indicates that the market is maturing and being able to distinguish between good and bad assets, a situation which is in fact healthier than the un differentiated, everywhere-rising trend seen in 2023 and 2024. Regulation Has Genuinely Changed Since the Last Downturn The most recent major adjustment in Dubai occurred in a market which had a deal with much less regulatory infrastructure than is the case nowadays. The system for escrow accounts when making off-plan payments, stricter requirements for developer licensing, and more thorough supervision by the Dubai Land Department have all helped to prevent the kind of speculative and undercapitalised development which caused actual harm in earlier cycles. While a correction can still happen, the sort of cascading crash caused by developer insolvency that took place in 2009 is now much less likely. What This Means If You’re Deciding Whether to Invest If you are one of the diaspora investors with whom we regularly deal—for example, when deciding between Dubai and [property back home in Kenya](/blog/dubai-real-estate-kenyan-investors), [Nigeria](/blog/dubai-real-estate-nigerian-investors) or other places—then the following circumstances are the ones that really matter when making your choice. A market growing by 5-10% with some softening in its weaker areas presents a very different risk level to one that is in real decline, and it also offers a different kind of opportunity compared to the years of inflated growth at 12-22%, in which it was easy to overpay without realizing it. The important practical lesson is that at the present time location and the choice of developer are more important than they have been at any time in the past few years; the risk involved in purchasing a property in an established area with good location and real demand from end-users is quite different from that of buying an off-plan unit in an area that is oversupplied simply because the payment plan seemed attractive. The Golden Visa aspect is also something that comes into play at this point. Even if the property purchase exceeds the qualifying amount, residency benefits are still available no matter what stage the market is at, which is one of the reasons why serious investors view Dubai property as something to hold for several years rather than as an investment to flip in the short term. For more details, see our guide on the [UAE Golden Visa via real estate investment](/blog/uae-golden-visa-real-estate-investment). How We Approach This With Clients Since the 2026 market strongly favours selectivity, our approach makes heavy use of actual performance data rather than the projected figures found in sales brochures, monitoring which specific communities and developers are actually retaining value and which ones are already showing signs of weakening. The fact that we work directly with Dubai’s established developers enables us to guide our clients to off-market properties in those parts of the market that are truly performing, rather than simply going for the areas where the most marketing money is being spent. Frequently

Uncategorized

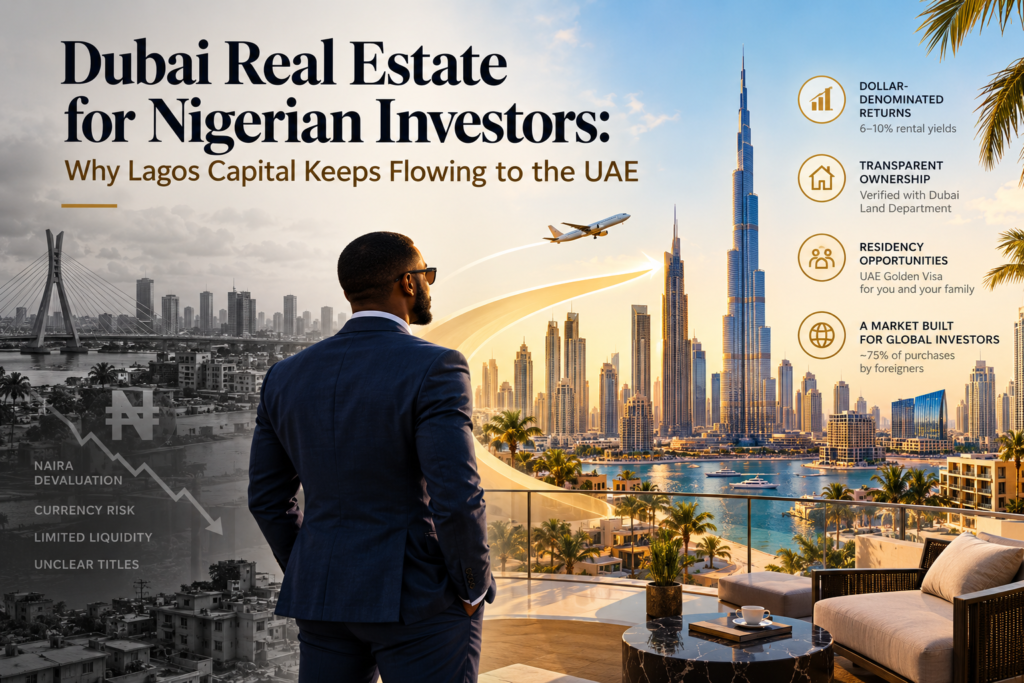
Dubai Real Estate for Nigerian Investors: Why Lagos Capital Keeps Flowing to the UAE

Everybody who has spent time in the business circles of Lagos or who is a member of the Nigerian investment groups operating in London, Dubai, and also in Lagos itself has come across some form of this exchange. The naira continues to lose value, real estate projects tie up capital in a currency that is difficult to hedge, and the properties which do perform well are generally held by those who already know someone with inside information on the deals. Among a particular group of Nigerian investors, the idea has now become almost inevitable: if capital has to be invested somewhere, it is increasingly being directed towards Dubai. It is not an uncommon pattern. For most of the last ten years Nigerian buyers have regularly been among the top group of overseas purchasers in Dubai’s property market, transaction volumes reaching billions of dirhams in good years. The change that has more recently taken place isn’t whether Nigerians are investing in Dubai, but rather how much capital is now going there and the way in which it is being deployed. The Naira Problem Nigerian Investors Are Trying to Solve It is important to make clear exactly what is behind this situation, since it is the reasons that are more important than the end result. The devaluation of the naira has been one of the most persistent factors causing a loss of wealth for Nigerian investors in the last few years, and although local real estate does have cultural and emotional value, it does not completely overcome this issue. Property in Lagos or Abuja is still priced and sold in a currency which can lose a considerable portion of its value over a short period of time, and the ability to actually sell when required—is generally not as quick as investors hope for. Dubai provides a structurally distinct option since the dirham has maintained a fixed exchange rate with the US dollar for more than ten years; as a result, an investor who holds a Dubai asset is not subject to the currency risk associated with an asset denominated in naira. This is not a bet against Nigeria, but rather a method of ensuring that not all of the assets an investor owns move in the same direction at the same time. What’s Actually Pulling Nigerian Capital Toward Dubai Dollar-Denominated Returns Without London or New York Prices For years, high-net-worth individuals from Nigeria have tended to choose London, New York, and Paris when looking for second homes and as a means of preserving their capital. Dubai provides a comparable offer in terms of dollar stability but at a much lower entry cost, since the average prices are considerably less per square foot than those in central London, yet it still provides good rental yields, these often being in the 6-10% range according to the area, which is well above the rates currently available in most established markets. Transparent Ownership You Can Verify Remotely All freehold transactions in Dubai are registered with the Dubai Land Department and this record can be checked independently, without having to rely on a personal relationship or the word of a lawyer. For investors who are used to dealing with land disputes or unclear titles in their home countries, this fact alone has a significant effect on their assessment of the risk. A Market Built for Foreign Capital About three-quarters of all property purchases in Dubai are made by buyers from abroad, so the whole transaction system—including the legal procedures, payment arrangements, and remote completion—has been developed to cater to investors who do not reside in the UAE. Nigerian buyers are not using a system meant for locals even though it does allow foreigners; rather, the system has in fact been designed for a type of buyer like this. Residency Attached to the Right Purchase That is where the investment case goes beyond considerations of return. In Dubai, buyers who purchase property worth a certain amount can qualify for the UAE Golden Visa, which grants the investor and their immediate family long-term residency linked to the property rather than having to go through a separate and lengthy application procedure. We explain in our guide on the [UAE Golden Visa obtained via real estate investment](/blog/uae-golden-visa-real-estate-investment) just how the thresholds and the process function. For Nigerian families who are currently considering international schooling or living abroad, this point often changes a simple rental purchase into a long-term relocation choice. A Pattern Playing Out Across the Continent Nigeria is not entering the Dubai market on its own. The same reasoning has caused a considerable influx of African capital into Dubai’s property sector, Kenya’s investors now own one of the largest proportions of Dubai’s real estate that is African in origin, and we have set out in full detail [the reasons why Kenyan investors are taking this step](/blog/dubai-real-estate-kenyan-investors). Investors from Zimbabwe, South Africa, Ghana, and Egypt have all taken a course that is almost identical to this one, being drawn by the stability of their currencies, the possibility of clear ownership, and returns that can be verified and stand up to real examination. Nigerian investment is just one of the biggest and most steady components of this wider trend. What This Looks Like Done Properly The Nigerian investors who achieve success in Dubai are those who view it as a real portfolio decision, not merely a response to pressure on the naira. Such investors should take into account the true net yield after deducting service charges, select a developer who has a real record of successful deliveries rather than one with the most aggressive marketing, and arrange the purchase with appropriate legal and tax advice on both the Nigerian and UAE sides. Since we deal directly with the established developers in Dubai, we are able to provide Nigerian clients with off-market inventory and actual performance data for particular buildings, as opposed to the projected figures found in a glossy brochure. Frequently Asked Questions Is it legal for citizens of Nigeria to

Uncategorized

Buying Property in Dubai From Australia: What Investors Need to Know in 2026

If you spend any length of time going through the listings of property investment firms on Facebook or LinkedIn you’ll see a trend that was by no means as widespread five years ago. Agencies of a small scale based in Melbourne, as well as well-known offices in Sydney, are all now advertising Dubai apartments. The argument they present is always essentially the same: that Sydney’s returns are hovering at about 2% to 3%, that entry prices are at record levels, and that the overseas market is apparently outperforming in almost every respect that matters. The pitch isn’t incorrect, really, but it by no means gives the full situation, and many Australian investors are sending money to Dubai for property on the basis of a slick brochure without realising how the mechanics function once you’re outside the Australian system. Therefore, let’s look at it properly. Why This Conversation Is Happening at All The figures in question are truly impressive, which is the reason why what was once just a specialist topic is now appearing in general property conversations. In popular areas such as Jumeirah Village Circle, Business Bay, and Dubai Hills, Dubai’s rental market regularly offers gross yields between 6% and 9%, as against the 2% to 3% that many Australian investors are accustomed to in Sydney and Melbourne. When you also take into account the absence of income tax, capital gains tax, and property tax on individually owned residential units, it becomes easy to see why the attraction is so great. The Australian dollar has similarly fared quite well against the dirham over recent periods, making the entry prices seem more within reach than they would have otherwise. That doesn’t mean it’s a simple one-for-one exchange, though. It’s a different market, operating under different rules, and the specifics are important. Where Australian Investors Commonly Get It Wrong Comparing Gross Yield to Net Yield This is most likely the commonest error. The yields advertised in Dubai are nearly always gross and do not take into account service charges, vacancy periods, or management fees. Australian net yields are generally given after most of these expenses have been deducted. If you compare the two like this, Dubai appears to be better than it actually is when you make a fair and direct comparison. While the figure from Dubai is still usually higher, the difference is not as big as the figures in the headlines indicate. Assuming an Australian Bank Will Finance It There is a widespread belief that it is possible to finance a property in Dubai as one would finance a second investment property in Australia—by means of refinancing or by having a local lender provide an overseas mortgage. In reality, Australian banks do not offer financing for purchases in Dubai, and potential buyers must therefore pay in cash, use a payment plan arranged by a developer, or secure financing directly from a UAE bank as a non-resident, which involves its own eligibility requirements and generally allows a loan-to-value ratio of no more than 50%. Not Realizing Negative Gearing Still Applies There’s one point that is to the advantage of Australian investors and is frequently neglected. When you take a loan to pay for a property in Dubai and your interest payments and other expenses are more than the rental income you receive, these losses can usually still be deducted from your Australian income—this being the same principle of negative gearing that applies to a local investment property. It is important to talk to your accountant about this particular situation since the details are slightly different in the case of an overseas asset. Treating the Golden Visa as Automatic Just because you buy a property doesn’t mean that you automatically obtain residency; instead, you have to make a separate application with its own set of requirements. For the longer-term visa category as of 2026, the property investment route usually requires a minimum investment of 2 million AED, and your eligibility will depend on the ownership structure, the financing arrangements, and the valuation, not merely on the purchase price stated in the contract. We explain in detail how this process works in our guide to the UAE Golden Visa through real estate investment. The Power of Attorney Question If you are buying property in Australia without visiting Dubai, you will probably need a Power of Attorney in order to carry out the transaction over a distance. Starting in 2024, Dubai’s notary service has begun to accept live video Power of Attorney appointments for people who live in Australia, thus making an embassy visit unnecessary in many instances. Nevertheless, the appropriate procedure will vary according to the particular document, the bank or developer concerned, and the requirements of the Land Department, so it is not suitable to use a generic Power of Attorney template which is available online. It is one of the points that should be got right from the beginning rather than being corrected later on. How This Fits Into a Broader Australian Trend We have also looked in detail at the Sri Lankan-Australian community’s entry into the Dubai property market, and this trend can be observed more widely among Australian investors as a whole, not just within diaspora groups. The same basic reasoning applies: the local yields no longer compare as favourably as they used to, entry prices have caused a large number of investors to get out of their second Australian property, and there is a market abroad which provides a truly different risk and return scenario. What This Looks Like Done Properly The people who achieve a good return on a property purchase in Dubai are those who view it as a real investment choice, not merely someone chasing yield based on an advertisement from Instagram. This involves knowing the true net return once service charges and vacancy have been taken into account, ensuring that the property ownership document (POA) and the financing arrangement are correct from the beginning, and selecting a developer who has a real track

Uncategorized

Why South African Investors Are Buying Property in Dubai

Anyone who is reading this from Johannesburg, Cape Town, Durban or Pretoria will already know why South Africans have begun to look elsewhere for their investment money. The rand has had a difficult decade, power outages have become a regular entry in household budgets for many years, and crime figures have started to appear in conversations which used to be about school fees and retirement arrangements. All of this is nothing new to people who have experienced it. Recently the main point that has changed is the destination of that capital. More and more South African investors, entrepreneurs, professionals, and high-net-worth families have been directing their money into property in Dubai, not as a speculative move, but as a deliberate way of hedging against the very risks they are trying to escape at home. The Push Factors Are Local, the Pull Factor Is Dubai It is important to be honest about the reasons for this change rather than conceal them. South African investors are not abandoning the local property market because Dubai has a more effective marketing team; they are reacting to genuine and particular problems, such as currency depreciation which gradually diminishes wealth measured in rands, the political and economic uncertainty which makes long-term planning more difficult, and the general feeling that too much of the household balance sheet is dependent on the economic situation in one country. Dubai deals with all of those concerns in a fairly direct manner by having a currency linked to the US dollar instead of one susceptible to volatility in emerging markets, by providing a tax system that includes no capital gains tax or annual property tax, and by offering a degree of political and economic stability which is now genuinely rare to come by in one package. What’s Actually Driving South Africans to Dubai Specifically A Hedge Against Rand Volatility By holding an asset which is priced and traded in AED and which is linked to the dollar, South African investors gain exposure to movements other than those of the rand. This is not a move against South Africa, but rather an attempt to ensure that not all of the assets an investor holds rise and fall at the same time. Returns That Outperform Local Alternatives The rental market in Dubai has always provided high yields in well-established areas and, when the costs involved are taken into account, has usually beaten what South African investors achieve on domestic rental property, especially when maintenance, rates, and the actual difficulty of managing tenants from a distance are considered. Easier Than It Sounds From Johannesburg or Cape Town It is here that a great many investors from South Africa unnecessarily hesitate. Since there are direct flights available from both Johannesburg and Cape Town, it has become genuinely possible for people to visit the site, and the purchase process – including virtual tours, e-signatures and international transfers – is now simple enough that in many cases the buyer has no need to travel at all. Furthermore, financing is often available to non-residents, so paying in cash is by no means the only way. A Golden Visa Attached to the Purchase It’s this point that usually leads clients to make their decision. If a person invests in property in Dubai above a certain amount, they become eligible for the UAE Golden Visa, which provides long-term residency for the entire family as a result of the purchase rather than having to go through a separate application. We explain in our guide on the [UAE Golden Visa obtained via real estate investment](/blog/uae-golden-visa-real-estate-investment) exactly how the thresholds and the process function. For South African families considering international schooling or looking at an alternative plan outside the country, the residency benefit is often just as important as the return on investment itself. One Thing to Plan Around: South Africa’s Exchange Control Rules It should be dealt with directly rather than ignored, as it is the only aspect which is truly specific to South Africa. Residents of South Africa are covered by exchange control regulations which specify the amount of capital that can be transferred offshore each year without needing extra approval. People who are serious about buying a property in Dubai should obtain appropriate advice from a financial adviser or a tax professional on how to properly arrange the transfer before deciding on a particular property, since making a mistake at this stage might delay or complicate an otherwise simple purchase. Part of a Wider Pattern South Africa is not going it alone when it comes to investing in Dubai. This same basic reasoning has been observed in the case of [Zimbabwean investors in the UK and South Africa](/blog/dubai-real-estate-zimbabwean-investors), [Kenyan investors](/blog/dubai-real-estate-kenyan-investors), and [Sri Lankan investors in Australia](/blog/dubai-real-estate-sri-lankan-investors-australia): since their domestic markets have become more difficult to plan for over the long term, they are looking for a destination that offers verifiable ownership, currency stability, and returns that can withstand real examination. The fact that South African investors are so noticeable is merely because they are one of the more visible elements of a much wider trend of diaspora and cross-border investment into Dubai. What This Looks Like in Practice When we talk to our clients in South Africa, the question they usually ask is this: what proportion of my capital should be invested and what purpose should it serve? After that, we focus on matching the investment to the client’s goals, their income, the potential for appreciation, or a future plan to reside there, and we shortlist the appropriate developments by referring to actual performance data not just to the attractive material in brochures. The reason is that since we work directly with the developers, we can make our South African clients aware of off-market inventory before it is made available to the general public. Frequently Asked Questions Can South African citizens purchase property in Dubai while residing there as foreign nationals? Yes, South Africans are able to buy property in the designated investment areas of Dubai with full ownership

Uncategorized

Why Kenyan Investors Are Choosing Dubai Real Estate Over Nairobi Property

Ask around Nairobi’s business circles, or in any of the Kenyan WhatsApp groups running out of Dubai, London, or the Gulf, and you’ll hear the same story on repeat. Someone sent money home for a plot in Kiambu or Thika. A relative was supposed to manage the build. Months later, the plot is still empty, or worse, someone else’s name has quietly appeared on the title. It’s such a common story that Kenyan investors have started treating it as a cost of doing business back home, something you plan around rather than something you can avoid. But increasingly, a different pattern has emerged. Rather than accepting that risk, Kenyans, both those working in the Gulf and those still based in Nairobi, have been redirecting serious capital into Dubai instead. Kenyans now hold the largest share of Dubai real estate investment among African nationalities, and it isn’t close. The Problem With Investing From a Distance None of this is really about Kenya being a bad place to invest. It’s about the specific challenge of investing in property you can’t personally oversee. Land fraud and encroachment remain real risks for anyone buying property in Kenya while living abroad, and title verification, while improving through platforms like Ardhisasa, still requires local legwork that’s hard to manage from Dubai, London, or wherever the investor happens to be based. Add to that a rental market where net yields, after management costs and vacancy periods, often land lower than the headline numbers suggest, and you start to see why so many Kenyans with capital to deploy are looking elsewhere for at least part of their portfolio. Why Dubai Specifically Dubai isn’t a random substitute. For Kenyan investors, it solves the exact problems that make Nairobi property difficult to manage remotely. A Title You Can Verify Without Being There Every freehold transaction in Dubai runs through the Dubai Land Department, and ownership records are checkable online, not something that depends on a lawyer’s word or a relative’s honesty. For investors who’ve dealt with disputed titles or encroached-upon land back home, this alone changes the calculation. Yields That Compete Directly With Nairobi Nairobi rental yields average around 7% before tax in strong areas, which sounds respectable until vacancy periods, management fees, and maintenance are factored in. Dubai’s established communities post comparable or higher gross yields, typically in the 5-9% range, with the added benefit of a far more liquid resale market if an investor needs to exit. Tax-Free Returns Dubai charges no personal income tax, no capital gains tax, and no annual property tax on individually owned residential property. For an investor comparing net returns across markets, that difference compounds meaningfully over a multi-year hold. A Genuine Path to Residency This is where things connect to something we’ve covered in detail elsewhere. Property investment above a set threshold in Dubai can qualify a buyer for the UAE Golden Visa, long-term residency attached directly to the purchase rather than a separate application process. We break down exactly how that works in our guide to the [UAE Golden Visa through real estate investment](/blog/uae-golden-visa-real-estate-investment). For Kenyan investors already spending significant time in the Gulf for work, this is often the detail that turns a rental purchase into a genuine long-term relocation option for the whole family. Not Just a Kenyan Story Kenya isn’t unique here, and it helps to see the pattern for what it is. We’ve written about the same shift happening among [Zimbabwean investors in the UK and South Africa](/blog/dubai-real-estate-zimbabwean-investors) and [Sri Lankan investors in Australia](/blog/dubai-real-estate-sri-lankan-investors-australia), and the underlying reasons are nearly identical every time: a home market that’s difficult to manage from abroad, and a search for a market with verifiable ownership, stronger currency stability, and returns that hold up under scrutiny. Dubai has positioned itself as the answer for diaspora capital across multiple regions, and Kenyan investors are one of the clearest examples of that trend, already the largest African investor group in the city’s property market. What This Looks Like in Practice Most of our Kenyan clients start the same way, they’ve either had a bad experience with property back home or watched someone close to them go through one, and they want to understand what a more transparent alternative actually looks like. From there, it’s a matter of understanding whether the goal is rental income, appreciation, or a future residency option, and shortlisting developments based on genuine yield performance rather than a sales brochure. Because we work directly with Dubai’s major developers, we’re also able to bring off-market inventory to Kenyan clients before it reaches the wider public listings, which matters in a market that moves as quickly as this one does. Frequently Asked Questions Can Kenyan citizens buy property in Dubai without living there? Yes. Foreign buyers, including non-residents, can purchase freehold property in Dubai’s designated investment areas regardless of where they currently live or work. How do Dubai’s returns actually compare to Nairobi? Nairobi yields average around 7% before tax in strong areas, while Dubai’s established communities typically post gross yields in the 5-9% range, often with lower ongoing management risk for an absentee owner. Is Dubai property investment safer than buying land in Kenya from abroad? It carries a different risk profile. Dubai’s title registration is centralized and independently verifiable, which removes much of the fraud and encroachment risk that affects land purchases managed remotely in Kenya. Can this qualify me for UAE residency? Yes, properties above the qualifying threshold can make you and your immediate family eligible for the UAE Golden Visa, a renewable long-term residency tied to the property investment. Do I need to be working in the UAE to invest? No. Investors based in Kenya, the UK, or anywhere else can purchase Dubai property and apply for the associated Golden Visa without needing to relocate first. Ready to Explore What Fits Your Goals? Whether you’re based in Nairobi, Dubai, or elsewhere in the diaspora, we can walk you through what’s currently available and how it lines up with

Scroll to Top